Tax Planning Software for Solo Accountants
Quick Answer Summary For a solo accountant taking on a first paid tax planning engagement, the best software is one that...
Read MoreWhen you sell an investment property, a business, or another highly appreciated asset, the capital gains tax can take a significant bite out of your proceeds. In 2026, long-term capital gains rates remain at 0%, 15%, and 20% depending on income, plus an additional 3.8% net investment income tax for high earners. For a business owner selling a company for $3 million with a $500,000 basis, a $2.5 million gain could trigger a federal tax bill approaching $600,000 or more before state taxes.
A Deferred Sales Trust is a specialized form of installment sale under IRC Section 453. Rather than selling an asset directly to a buyer and receiving the full proceeds, the seller transfers the asset to an independent third-party trust in exchange for a promissory note. The trust then sells the asset to the buyer and holds the proceeds. The trust makes scheduled installment payments to the seller over a defined period. When the transaction is a bona fide installment sale and the seller does not retain control over or unrestricted access to the proceeds, the eligible gain is generally recognized as the installment payments are received.
In a standard installment sale, the seller agrees to receive payments directly from the buyer over time, which carries risk: if the buyer defaults, the seller loses both the asset and future payments. The DST solves this problem by inserting a third-party trustee between the seller and the buyer. The trust receives the full sale proceeds from the buyer immediately. The trust then makes payments to the seller according to the promissory note terms. The seller’s payments depend on the trust and its investment portfolio rather than the buyer’s ongoing payment performance, shifting, but not eliminating, the seller’s risk.
The trust can invest the proceeds in a diversified portfolio including REITs, bonds, annuities, securities, and other prudent investments. The trust’s assets and investment returns fund the ongoing installment payments to the seller.
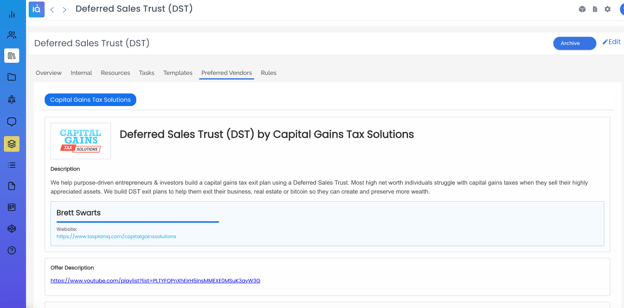
TaxPlanIQ has over 130 advanced strategies, including the DST strategy with preferred vendors for implementation.
The OBBBA, signed July 4, 2025, did not change the long-term capital gains rates for 2026. The rates remain at 0%, 15%, and 20% based on taxable income thresholds, which were adjusted for inflation.
For 2026, the long-term capital gains rate thresholds are:
For married couples filing jointly, the 0% rate applies to taxable income up to $98,900. The 15% rate applies from $98,901 to $613,700. The 20% rate applies above $613,700. For single filers, the 0% rate applies up to $49,450, the 15% rate from 49,451 to 545,500, and the 20% rate above $545,500.
The 3.8% net investment income tax continues to apply to net investment income for individuals with modified AGI above $200,000 (single) or $250,000 (married filing jointly). This means a high earner realizing a large capital gain in a single year can face a combined federal rate of up to 23.8% on long-term gains before state taxes. In states with capital gains taxes, the effective combined rate can exceed 30%.
Important: The OBBBA did not modify IRC Section 453. The installment sale rules that underpin the DST remain fully intact for 2026.
Short-term benefit: By deferring eligible capital gains recognition, the seller avoids paying the entire associated capital gains tax in the year of sale. If a seller would have owed $500,000 in capital gains taxes at closing, that $500,000 continues to be invested inside the trust and generating returns rather than going to the IRS immediately.
Long-term benefit: The money that would have been paid in taxes continues compounding inside the trust. Over a 10-year payment period, the after-tax outcome for the seller can be meaningfully larger than an outright sale with immediate tax payment, depending on the trust's investment performance and the seller's marginal tax rates in the years payments are received.
The math is straightforward: a dollar of tax deferred today and invested for 10 years at a conservative 6% annual return becomes $1.79 before fees and taxes. That is the compounding power of tax deferral at work.
The DST can be used to defer capital gains from the sale of a wide range of asset types, including:
The installment method generally cannot be used for inventory or for stocks and securities traded on an established securities market.
This is a key advantage over the 1031 exchange, which is limited to like-kind real estate and requires strict 45-day property identification and 180-day closing timelines. The DST has no equivalent reinvestment or timing constraints.
|
Factor |
Deferred Sales Trust |
1031 Exchange |
|
Asset types |
Various qualifying appreciated assets, subject to Section 453 exclusions |
Like-kind real estate only |
|
Reinvestment requirement |
None |
Must reinvest in like-kind property |
|
Timing rules |
Flexible |
Strict 45-day / 180-day deadlines |
|
IRS explicit approval |
Based on Section 453; no formal ruling |
Explicitly authorized by IRC Section 1031 |
|
Tax outcome |
Deferral via installment payments |
Full deferral if properly completed |
|
Liquidity |
Structured payments over time |
Capital remains invested in replacement real estate, although the property may generate cash flow |
|
Seller risk |
Trust investment performance |
Market and property risk of replacement asset |
|
Estate planning benefit |
Yes, potential estate freeze |
Limited |
The 1031 exchange remains the stronger option when a client wants to stay invested in real estate and can meet the timeline requirements. The DST may be the better fit when a client wants to exit a real estate or qualifying non-real-estate asset, diversify into other investments, or cannot identify a suitable replacement property within the 1031 timeline.
Who Qualifies for a Deferred Sales Trust?
Not every client is a DST candidate. The strategy is designed for transactions where the economics justify the setup and ongoing costs. Although IRC Section 453 does not establish these minimums, DST providers commonly use economic guidelines such as:
Below these minimums, the setup costs and administrative complexity typically outweigh the tax savings. Above them, the tax deferral benefit can be substantial enough to make the strategy highly attractive.
Ideal candidates include business owners planning a company exit, real estate investors selling appreciated commercial or residential investment property, owners of qualifying private business interests with very low basis, and sellers who cannot identify a suitable 1031 exchange replacement property within the required timelines.
Download 5 Secrets to Growing a $5M Advisory Firm
While every DST requires qualified legal and tax counsel, the general process follows these steps:
Step 1: Evaluate feasibility. Before any sale agreement is signed, the DST structure must be analyzed. The trust must be established before closing. Once the seller receives the sale proceeds personally, the opportunity to use a DST is permanently lost.
Step 2: Establish the trust. Work with qualified tax counsel and an independent DST trustee to draft the trust documents, installment note, and Deferred Sales Agreement.
Step 3: Execute the Deferred Sales Agreement. The DSA specifies the purchase price, interest rate, payment term, and structure of the promissory note the seller will receive.
Step 4: Close the sale. At closing, the seller transfers the asset to the trust. The buyer pays the full purchase price to the trust. The seller receives a promissory installment note from the trust rather than cash.
Step 5: The trust invests and pays. The trustee invests the proceeds in a diversified portfolio. The trust makes installment payments to the seller per the note terms. Each payment may include a return of basis, taxable gain, and interest. The gain portion is recognized as payments are received, while interest is generally taxed as ordinary income.
Step 6: Estate planning integration. With proper planning, a fixed-value installment note may provide estate-planning opportunities. However, the note generally remains an asset of the seller’s estate, and the remaining deferred gain may have tax consequences for the seller’s heirs.
The DST is not a free strategy. Typical fees include:
These costs must be factored into the ROI analysis presented to clients. For a $2 million gain with a 20% federal rate plus 3.8% NIIT, the deferred tax liability is approximately $476,000. On a transaction of that size, setup fees ranging from $25,000 to $30,000 would equal approximately 5.3% to 6.3% of the deferred federal tax liability, before considering ongoing trustee and investment-management fees.
The DST is a powerful strategy, but accountants have a professional obligation to present the full picture.
No explicit IRS ruling: The DST structure is not formally endorsed by the IRS through a specific public ruling. It is based on the installment sale rules under Section 453, but the "Deferred Sales Trust" terminology does not appear in the Internal Revenue Code. Proper documentation and a qualified trustee are essential to withstand potential IRS scrutiny.
Limited access and reversibility: Once the trust has sold the asset to the ultimate buyer, the original sale generally cannot simply be reversed. The seller holds an installment note rather than the sale proceeds and does not have unrestricted access to the trust’s portfolio. Any acceleration or modification of the note could also have tax consequences.
Irrevocability: Once the asset is transferred to the trust, the structure cannot be unwound. The seller receives installment payments rather than a lump sum, and full liquidity is not available.
Trust investment risk: The seller's ongoing payment stream depends on the trust's investment performance. A poorly performing portfolio could affect the trust's ability to meet its payment obligations, though a well-structured trust with conservative investments significantly reduces this risk.
Setup timing is critical: The trust must be established and the asset transferred before the closing. If the seller has already constructively received the proceeds, the DST opportunity is permanently lost.
Depreciation recapture timing: For depreciable property, any portion of the gain treated as ordinary income under the depreciation-recapture rules must generally be recognized in the year of sale rather than deferred under the installment method. The remaining gain may include capital gain or unrecaptured Section 1250 gain, depending on the type of property and its depreciation history.
A note from Dr. Jackie Meyer, founder of TaxPlanIQ
I have sat on both sides of this conversation. As an accountant, I have helped clients navigate the tax consequences of business exits. And as a business owner, I have navigated the same questions myself.
In The Balanced Millionaire, I share the story of how I ultimately sold my own firm. I had been building it for years, shifting from a compliance-heavy practice to a fully advisory-focused model, repricing clients based on value, systematizing everything. I had built a seven-figure practice with strong recurring revenue, documented processes, and a team that could operate without me being on-site every day. That was the version of the firm a buyer would actually pay a premium for.
When the time came to sell, I was able to close at 1.5 times annual recurring revenue, a meaningful premium over the typical one-times valuation for owner-dependent practices. The buyer was paying for a machine, not just a client list.
What I did not always have in my earlier years was a proactive exit tax strategy built into my own planning. That is something I now think about differently. The question of what happens to the tax liability when you sell a business should not come up at the closing table. It should be something an accountant raises two to five years before a client is even thinking about exiting, so the right structure is in place when the moment arrives.
The Deferred Sales Trust is one of the most powerful tools for that conversation. I had a real estate investor client with multiple properties across several states, working with a compliance-only accountant who filed returns but never planned proactively. When I reviewed his situation, I found not just depreciation and cost segregation opportunities but also the beginning of an exit strategy framework that included thinking ahead about how he would eventually unwind those positions without triggering a tax event that wiped out years of gains in a single year.
I put together a strategy that would save him more than $75,000 annually. I charged $25,000 for the advisory engagement, giving him a 200% ROI before even modeling the exit-year savings.
That is the opportunity that capital gains planning represents. A client planning to sell a business or investment property with $1 million or more in embedded gain is looking at a six-figure tax event. The accountant who raises that conversation early, presents the options clearly, and builds a plan around it becomes indispensable. The accountant who waits until after closing to deliver the news has lost the advisory opportunity entirely.
If you are working with a client who is interested in setting up a Deferred Sales Trust, TaxPlanIQ can help. Our software provides an elaborate DST strategy framework to help you and your client navigate the rules and regulations. We have also partnered with Capital Gains Tax Solutions, an industry-leading Deferred Sales Trust Investment Trustee Service that helps high-net-worth individuals and businesses with complex financial assets minimize their capital gains tax exposure. This partnership gives you access to their extensive knowledge and experience in setting up DSTs.
Get a demo of TaxPlanIQ and see how it helps you and your clients create a clear Deferred Sales Trust strategy and a comprehensive wealth plan.
Interviews, tips, guides, industry best practices, and news.
Quick Answer Summary For a solo accountant taking on a first paid tax planning engagement, the best software is one that...
Read MoreTax planning as an RIA service Adding tax planning to an RIA means adding a forward-looking service that reviews a clien...
Read MoreQuick Answer Summary TaxPlanIQ is tax planning software that turns a client's 1040 into a client-ready proposal showing ...
Read MoreThe best tax projection software options for most firms in the United States are softwares that answer client questions....
Read MoreQuick Answer Summary To build a tax plan for an S corp owner, set a defensible reasonable salary first, then stack three...
Read More